Monday, June 24, 2013

Debt Relief = Income

Mortgage Relief.pngMany times a homeowner might feel relieved being out from under the obligation of a mortgage they can’t afford even though the property was lost due to foreclosure or short sale. If a lender cancels or forgives debt, a taxpayer must include the cancelled amount in their income for tax purposes depending on the circumstances. The tax significance could be serious.

Congress enacted the Mortgage Relief Act specifically to help homeowners who might be affected in the housing crisis that started approximately in 2007. The Act expired on 12/31/12 but was temporarily extended by Congress until December 31, 2013.

This relief only applies to a taxpayers’ principal residence which does not include second homes and investment property. The maximum amount is limited to $2 million of mortgage debt forgiveness or $1 million if filing separately.

Another provision is that the debt relief is limited to acquisition indebtedness used to buy, build or improve the property. It excludes cash equity loans whether made separately or in a refinance of the original mortgage.

Due to the serious consequences involved in short sales and foreclosures, it is advised that homeowners faced with this possibility should seek expert advice from their legal and tax professionals.

Saturday, June 22, 2013

100 Acres Woods Road, Clare County - SOLD!

Great Hunting Camp that can also be sold as 60 acres, 40 acres and 18 Acres in NE Clare County!

SOLD!


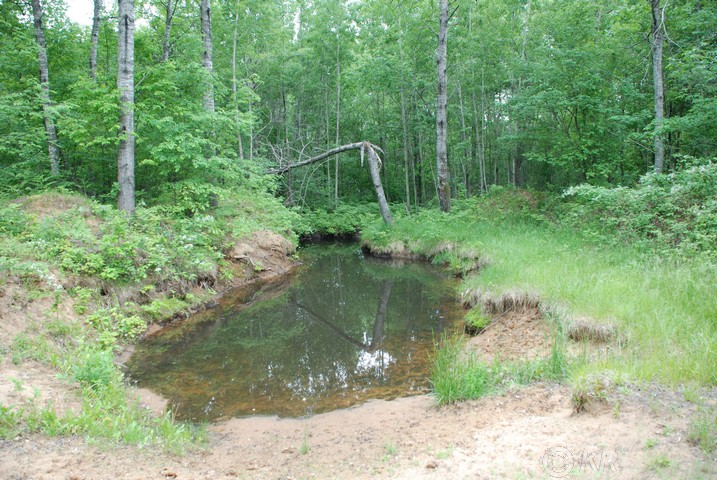
Are you looking for a secluded hunting camp with lots of rolling acreage, mature trees, food pots, established hunting blinds and lots of wild game? Then you may have just found it! This beautiful property is a hunters delight with several food plots, trails and blinds. Lots of deer in the area. 


The sellers had a professional deer management person come in and prepare the deer habitat. Several small clear cuts were made to promote desirable deer habitat, but it also great for turkey, grouse, woodcock and other local wildlife. There is also a small pond near one of the food plot areas to provide water to deer. There is a nice log sided cabin with a bunk room, wood stove and a kitchenette area. Great place to make hunt camp memories with family and friends. You can make this your own!


Monday, June 17, 2013

Serious Buyer

Serious Buyer2.pngInventory is dramatically shrinking and it is commonplace in many markets to have multiple offers on a home. While the sellers would prefer to be able to choose the best offer for them, it can be incredibly frustrating for the buyers who might consider the following tips to get their offer accepted.
1. Remove the uncertainty that you may not be approved for a mortgage by having a pre-approval letter from your mortgage company.
2. Show your sincerity by increasing the normal amount of earnest money customary for the area and price of the home. The earnest money will be applied toward your down payment and closing costs. Consider placing even more money in escrow when the contingencies have been met.
3. Specify a closing date in the contract but acknowledge that you can be flexible to accommodate the sellers moving date. If it becomes an issue, it still must be mutually agreed upon.
4. Make the contingency periods shorter if possible to make the seller feel that they’ll know sooner that the offer is solid.
5. If the contingency really isn’t important to you, leave it out of the offer. The more contingencies included in a contract, the more the seller will feel might happen to keep it from actually closing.
6. Write a personal note to the seller explaining why you like and want their home. Consider including a picture of your family and pets.
7. Physically sign the offer with a felt tip pen of contrasting color. You’d be surprised how this adds a personal touch to the offer.
Offer a fair price for the property in your initial purchase agreement. It shows sincerity and good faith that you’re actually trying to purchase the home and not trying to take advantage of the seller. The old adage that you can always go up later may never happen if there are multiple offers on the property in the beginning.

Sunday, June 09, 2013

Renters Want to Buy

FNMA NHS.pngFannie Mae, in a recently released study, states that consumer attitudes continue to be favorable about homeownership, particularly with the younger generations, ages 18 to 34. Slightly over half of them think that owning makes more sense than renting when comparing the financial and lifestyle benefits.

90% of aspiring owners expect to purchase a home someday and slightly over half think they’ll do it within five years. The primary challenges are having sufficient savings and the difficulty of getting a mortgage today. Younger renters see renting as a temporary stepping stone toward homeownership.

Homeowners are far more likely than renters to be “very positive” about their housing experience. Some of the benefits identified are:

• Having control over what you do with your living space
• Having a sense of privacy and security
• Having a good place for your family or to raise your children
• Having the best investment plan
• Living in a nicer home
• Building up wealth
• Saving for retirement
• Living in a place where you and your family feel safe
• Feeling engaged in your community

To satisfy a buyer’s doubts about qualifying for a mortgage, make an appointment with a trusted mortgage professional. If you’d like a recommendation at no cost or obligation, please contact me at iviebaker@kehoerealty.com.  Check out this Rent vs. Own to see the real cost of owning a home.

For more information about the Fannie Mae survey in presentation form, Click Here.


Monday, June 03, 2013

What's It Worth?

Question button.pngHow much is a one carat diamond worth? Anyone who has shopped for one knows that the price could have a significantly wide range of value. It's been said that purchasers  should consider the color, cut, clarity and carat size to compare stones but when it gets down to decision time, buyers still want to know “how much is it worth?”

Real estate valuation can be equally as confusing to the public. There are three commonly used tools that today’s home buyers rely on to make decisions but they vary significantly in the methods used to make the determination as well as the possible final consideration.

Appraisals are an opinion or estimate of value based on specific guidelines made by individuals who are licensed and possibly certified. Buyers and sellers may be reluctant to engage an appraiser because there is a fee of several hundred dollars that must be paid in advance even if no sale is ever consummated.

A Broker’s Price Opinion (BPO) as defined by the National Association of REALTORS® is an “estimate of the probable selling price of a property.” The Dodd-Frank Act describes a BPO as “an estimate…that details the probably selling price of a particular piece of real estate property and provides a varying level of detail about the property’s condition, market, and neighborhood, and information on comparable sales, but does not include an automated valuation model.”

A Comparative Market Analysis (CMA) is a commonly used tool of salespeople to provide information to buyers and sellers to facilitate a sale. In most cases, it would be difficult to distinguish a CMA from a BPO because the steps considered are essentially the same and practitioners commonly use the terms interchangeably.

Another method called Automated Value Model (AVM) use software to search available data on the Internet to arrive at an approximation of value. Zestimates found on the Zillow site use this method. AVM’s may not consider all the market activity such as MLS sales and active listings. They can’t make adjustments based on human experience and market knowledge.

For what it’s worth, a buyer or seller might want to acquire as much current and factual information as possible from a trusted real estate professional familiar with the market before making a decision on the largest single asset most people acquire.

Monday, May 27, 2013

Will the "Good Life" Be Ready When You Are?

Life of Riley Index.pngThe Life of Riley was a TV show from the 50’s starring William Bendix but the title’s origin came from an expression meaning that a person was living the “good life.” Most people envision themselves living the good life by retirement but don’t really have a plan to get there.

There’s a rough rule of thumb used to estimate how much net worth a person would need by the time they retire to generate a certain income. The target annual income is divided by a safe, conservative yield to determine the investable assets needed.

A person who wanted $100,000 annual income generated from a 5% investment would need investable assets of $2,000,000. If a person had $500,000 now, they would need to accumulate $1.5 million more by the time they retire. If it was estimated to be 15 years away, they would need to save about $100,000 a year, each year until retirement.

It is a sobering example that could be depressing without a plan. It might be easy to say, “I should have started sooner” which may be true but there is still hope.
Gradually, over the next several years, accumulate rental property and allow the tenant to retire the debt for you. The equity in each property will grow from the amortization of the loan each time a payment is made. It also grows as the property increases in value due to appreciation.

Single family homes as rentals offer the investor an opportunity to meet their retirement and financial goals for the following reasons:

  • The ability to borrow large loan-to-value mortgages
  • At fixed interest rates
  • For long terms (easily up to 30 years)
  • On appreciating assets
  • With significant tax advantages
  • And reasonable control not offered by alternative investments.


Monday, May 20, 2013

Breathe Easy

iStock_000020770516XSmall.jpgThe benefits of regularly changing the heating and air-conditioning filters are obvious to homeowners; the real challenge is creating a system to make sure it gets done. 

A reasonable schedule would be to replace it with a new one-inch pleated filter every 60-90 days. Households with shedding pets should consider replacing them every month. Some people change their filters every month when they pay their electric bills.  A simple system would be to set a recurring appointment on your calendar like Outlook or Google.

Filters trap dust, mold and bacteria which can directly affect the air quality and play havoc with your allergies. When a filter is dirty, it prevents proper airflow and allows dust, dirt and allergens to blow through your home. Changing your filter regularly helps to avoid maintenance, improves equipment life and produces increased energy savings.

When shopping for filters, it’s understandable to look for the best bargain but the cheapest price may not be the best choice. When purchasing, recognize that HEPA-rated and HEPA-type filters are not the same thing. HEPA stands for high-efficiency particulate air. A HEPA filter meets or exceeds standards for efficiency set by the U.S. Department of Energy. Most HVAC contractors recommend HEPA filters.

Some filters need to be changed monthly and other types have manufacturer recommendations of every three months. An alternative to disposable filters are the permanent, washable types. These will cost more initially but because you can clean them and re-use them, eventually, you’ll recapture the cost and realize savings.


Monday, May 13, 2013

Whose Commission Is It?

home price.pngOne of the most common reasons buyers want to deal directly with the seller is because they feel they can save the commission. It’s a valid consideration but interestingly, it’s the same reason the seller isn’t employing an agent.

Both parties cannot save the commission. The buyer feels they have earned it because they’ve had to find the home, determine its value and negotiate with the seller. They had to arrange their own financing, title and inspections.

The seller equally feels that they have earned the commission because they too have had to research value, financing and title work.  They have incurred all of the marketing expenses and have invested hours upon hours to be available to show the property, hold open houses and answer inquiries. 

There is certainly value in all of the things that buyers and sellers are willing to do.  However, only one person can save the commission assuming the buyer and seller can reach a written agreement.

The Profile of Home Buyers and Sellers survey reports that 14% of sales were For-Sale-by-Owners in 2003 and 2004 compared to just 9% in 2012. The trend shows that agent-assisted sales rose to 88% in 2012 from 82% in 2004.

The three most difficult tasks identified by for-sale-by-owners is attracting potential buyers, getting the price right and understanding and performing the paperwork. When surveyed, sellers most value the home selling in an anticipated time frame and for an expected amount.

Experienced, third-party advocates helping buyers and sellers is a valuable contribution to the transaction which may determine whose commission it is.

Sunday, May 05, 2013

"Please take our offer..."

iStock_000005895710XSmall.jpgIt’s interesting that the housing climate has changed so quickly. Some buyers, who think they’re still in the driver’s seat, find the market is now going up and they’re losing the home that they really want.

Multiple offers are increasingly more common and buyers are frustrated because even full-price offers don’t guarantee that they’re going to get the home. In an effort to personify a contract offer and add emotional appeal, buyers are including a personal letter to the seller.

In most cases, the seller wants to maximize the net proceeds from the sale by getting the highest price with the least expenses and an assurance that the home will actually close on time without surprises. When a seller is faced with multiple offers that may be close to the same net, an emotional appeal might make the difference in them accepting a particular offer. That’s where the letter comes in play.

It should be a relatively short letter that gets to the point. The tone of the letter should be humble while positive and definitely, shouldn’t mention that you may have lost other homes due to multiple offers.

  1. Try to identify a common feature or characteristic of the home that is important to the seller and you.
  2. Don’t criticize the home or tell them about all of the improvements you need to make to justify your offer.
  3. Do verbalize why living in this home is important to you and your family.
  4. Assure the seller that you can indeed qualify for the home and that if they accept your offer, the sale will be consummated.

After writing the letter and eliminating the non-essential parts, read the letter a few times to your spouse or friend. Polish the verbiage and check the spelling and grammar. If your handwriting isn’t attractive and easy to read, print it. Use nice paper to appeal to the tactile senses. Attach the letter to the offer so they’re considered simultaneously.

Being pre-approved with good credit, adequate financial resources, good employment, sufficient earnest money and a reasonable offer with minimum contingencies will favorably position you. A personal letter might be the deciding factor in your favor.

Monday, April 29, 2013

5369 Jerry, Gladwin MI - FORECLOSURE by Grass Lake

Nice Cabin with Knotty Pine Interior

2 Bedrooms, 2 Baths

Just $12,500


Nice cabin/cottage for a getaway. Open floor plan and knotty pine walls in living room/dining area/kitchen. Has 2 bedrooms and 1 bathroom. Across the street from access and view of the lake. Near thousands of acres of state land. Has shed in back yard. Centrally located between Gladwin and Houghton Lake. In a great recreation area. Sold "AS IS

Cut Refinancing Expenses

iStock_000016148905XSmall(er).jpgEvery single day, homeowners who are excited about lowering their rate have a tendency to ignore the refinancing costs because they’re being rolled back into the new mortgage. If the payment is lower than what they’re currently paying and there’s no money out of pocket, it seems like a good deal.

Refinancing your home because a lower rate is available is one thing but the closing costs associated with that new loan could add several thousand dollars to your mortgage balance. By following some of the suggestions listed below, you may be able to reduce the expense to refinance.

•  Tell the lender up-front that you want to have the loan quoted with minimal closing costs.
•  Check with your existing lender to see if the rate and closing costs might be cheaper.
•  If you’re refinancing a FHA or VA loan, consider the streamline refinance.
•  Shop around with other lenders and compare rate and closing costs.
•  Credit unions may have lower closing costs because they are generally loaning deposits and their cost of funds is less.
•  Reducing the loan-to-value so that mortgage insurance is not required will reduce expenses.
•  Ask if the lender can use an AVM, automated valuation model, instead of an appraisal.
•  You may not need a new survey if no changes have been made.
•  There may be a discount on the mortgagee’s title policy available on a refinance.
•  Points on refinancing, unlike purchase, are ratably deductible over the life of the loan.
•  Consider a 15 year loan. If you can afford the higher payments, you can expect a lower interest rate than a 30 year loan and obviously, it will build equity faster and pay off in half the time.

A lender must provide you a list of the fees involved with making the loan within 3 days of making a loan application in the form of a Good Faith Estimate. Every dollar counts and they belong to you.


1975 Meadowview, Gladwin MI - SOLD!

Large Home on over 4 Acres with Lake Access to Lake Four!

4 Bedrooms, 2 Bath

SOLD


Spacious rambling ranch on nearly 5 acres near Lake Four. Home has 4 bedrooms, 1.5 bathrooms, family room and living room. Lots of room for a large family and large yard for the kids to play outside. Enjoy nature out your back door. Sold "As Is". Possible mortgage to qualified Buyer. Addendums and Proof of funds/Pre qualification Letter along with Sales Contract with all offers.

Sunday, April 28, 2013

4959 Ruby, Gladwin MI - SOLD!

Beautiful Waterfront Chalet on 2 Waterfront Lots with a LARGE BEACH!

3 Bedrooms, 2 Bath, 2 Car Detached Garage, plus a 30x40 Pole Barn

SOLD!


You will fall in love with this beautiful home on an extra large double lot, with a stunning view of Island Lake. This property features a large sandy beach, This Chalet is nestled in a wooded setting with lots of shade tress. Enjoy watching sunrises while watching Loons, Bald Eagles and a variety of other wildlife. This home also features a beautiful kitchen with granite counter tops and ash flooring in the kitchen, light birch cabinets, lots of windows, hot tub and sauna in the basement, oversized open deck, pole barn, two car garage with an upper storage area that could be converted into a guest loft. 


All of this sits on the west side of Island Lake, which is a no gas motors lake (elec motors ok), which is approx a 58 acre lake with approx 290 acres of association shared acreage that can be used for hunting, hiking and ATVing. Home is being sold with a ONE YEAR HOME WARRANTY!


Sunday, April 21, 2013

Shifting Debt to Tax Deductible

shift debt.pngThe Mortgage Interest Deduction is available to homeowners for up to $1,000,000 of acquisition debt on the combination of their first and second home.  They can also deduct interest on up to an additional $100,000 of Home Equity debt.

While Acquisition Debt is used to buy, build or improve a principal residence, the Home Equity Debt can be used for any purpose.  It can be used for educational or medical expenses, to purchase a personal car or boat, consolidate debts or pay off credit cards.

A homeowner with $15,000 of credit card debt at 19% and sufficient equity in their home could replace it with a home equity loan at much lower interest rate. Not only would the interest rate on the home equity loan be about 1/3 of the rate paid on the credit card, it’s would now be tax deductible.

If the taxpayer was in the 28% bracket, the net interest on a 6.5% loan would be 4.68% after tax benefits are considered.
Shifting personal debt to Home Equity debt can result in an interest deduction and probably, a lower interest rate. For more information see IRS Publication 936 page 10 and consult your tax professional.

Monday, April 15, 2013

When to Sell the Temporary Rental

Temporary Rental2.pngSome homeowners, who were not able to sell during the recession, chose to rent their homes instead.  In some cases, they didn't need to sell their home at the depressed prices and opted to rent it until the market recovered.

It's a valid strategy but there are time restrictions that could have serious tax implications for some homeowners.

The section 121 exclusion for gain in a principal residence requires that the home is owned and used as a main home for at least two years during the five year period ending on the date of the sale.  This allows a homeowner to rent their home for up to three years and still have some part of the exclusion available.

The sale of a home with a $200,000 gain that qualifies as a principal residence would result in no tax being paid by the owner.  Comparably, a rental property with the same gain could have a $30,000 or higher tax liability depending on the length of ownership and tax brackets of the investor.

The housing market has dramatically improved in the last year.  If you have a gain in a home that has been your principal residence and it has been rented less than three years, you might want to consider selling it while you qualify for the exclusion.

If you are considering a sale on your principal residence that has been rented, consult with your tax professional for advice on your specific situation.  For additional information, see IRS Publication 523.

Monday, April 08, 2013

Boomerang Buyers

Waiting periods.pngIt's estimated that 10% of the homes sold in 2013 will be to buyers who lost a home in the past five years.  Approximately 500,000 buyers who may have thought they wouldn't own a home anytime in the near future will be homeowners again.

It's estimated that several million of these previous homeowners will purchase again in the next eight years.  This kind of activity will contribute significantly to the housing recovery.

Some people thought that the housing crisis would cause a shift in values placed on owning a home but the boomerang buyers definitely don't support that theory.  Having a home of your own, where you can raise your family, share with your friends and feel safe and secure is still part of the American Dream.

The rising rents, increasing prices and low, low mortgage rates are also influencing buyers into the market.  In many cases, it is cheaper to own that to rent.

All new buyers, including those who have experienced foreclosures or bankruptcies, must have good credit history and the ability to repay the loan.  It just may not take as long to reestablish the credit as some would-be buyers might have thought.

Read more about Bidding Wars This Spring, Spring's Wild Card and Boomerang Buyers.

Monday, April 01, 2013

Bunch Your Taxes and Save

iStock_000016195030XSmall(er).jpgOne of the drawbacks to low mortgage rates is that the total interest and property taxes paid for the year may be lower than the standard deduction.  A little planning might be able to help you at least every other year.

Most homeowners know they can deduct their qualified mortgage interest and property taxes on their Schedule A of their 1040 tax return or to take the standard deduction if it is greater.  See Your Deduction...Your Choice.

Deductions are taken in the year that they're actually paid.  If a homeowner paid their 2012 property taxes in 2013, they would not be deductible on their 2012 tax return.  Then, if the 2013 property taxes were paid in 2013, both the 2012 and 2013 taxes could be deducted on the 2013 Schedule A.

By delaying the payment of the 2012 taxes until 2013, the combination of the 2012 and 2013 taxes might exceed the 2013 standard deduction and provide a higher deduction. 

Other Schedule A expenses such as charitable contributions and medical expenses may be bunched also.  From a practical standpoint, since most mortgage payments are due monthly, the mortgage interest would not be bunched.

This information should be discussed with your tax advisor to see how it might apply to your individual situation.  The key is you must be aware of the strategy early to be able to use it.

Friday, March 22, 2013

701 ANCHOR ST, Gladwin MI - SOLD!

Ready to Move Right Into! Cute Home on a Large Lot.
Property adjoins the Gladwin City North Park

1 Bedroom, 1 Bath, and Small Outbuilding with additional bathroom.

SOLD!


Attention investors and anyone downsizing! Move in ready! Cute and cozy describes this efficient 1-2 bedroom home on the outskirts of Gladwin. Quality remodel in 2009. Updates include new roof, windows, doors, vinyl siding, blown-in attic insulation, natural gas hot water heating system with pex plumbing, wood and ceramic flooring, oak kitchen cabinets, countertops and all appliances. Includes a metal shed for lawn equipment and an 11x15 outbuilding with a 1/2 bath and electric currently used for storage, that with some TLC, could be used as a guest house. Located on a large double lot, just 300 feet from North Park and the Cedar River walking trail, you'll enjoy the quiet neighborhood and the deer that stop regularly at the apple tree. 

Wednesday, March 20, 2013

Priced Out: New FHA rules may exclude some homebuyers

Fox and Friends | Fox News


Costly Changes in FHA Loans starting June 1st, 2013! BUYER BEWARE! Mortgage Insurance to be paid for the life of the loan! (Click link above to view the update by Bob Massi with Fox News)

Monday, March 18, 2013

Maintaining Comfort

iStock_000019943204XSmall(er).jpgSome people refer to the heating and air conditioning systems as the "comfort systems."  If you've ever had to be without one in the dead of winter or the heat of summer, lack of comfort may be an understatement.  Simple maintenance with a HVAC checklist is something that every homeowner can perform.

Periodically

  • Change your filter every 90 days; every 30 days if you have shedding pets.
  • Maintain at least two feet of clearance around outdoor air conditioning units and heat pumps.
  • Don't allow leaves, grass clippings, lint or other things to block circulation of coils.
  • Inspect insulation on refrigerant lines leading into house monthly and replace if missing or damaged.

Annual, in spring

  •  Confirm that outdoor air conditioning units and heat pumps are on level pads.
  • Pour bleach in the air conditioner's condensation drain to clear mold and algae which can cause a clog.
  • Avoid closing more than 20% of a home's registers to keep from overworking the system.
  • Replace the battery in the home's carbon monoxide detector.

Even with the attention that perfoming this list will provide, it is recommended that you have your units serviced annually by a licensed contractor.  Furnaces can be inspected for carbon monoxide leaks and preventative maintenance may help avoid costly repairs.  Click Here if you'd like a recommendation.